Indi Mortgage Logo

FORMERLY The Personal Mortgage Group

We dive deep into every detail and crunch the numbers,

ensuring you know exactly what you're doing and why.

Logo

FORMERLY The Personal Mortgage Group

We dive deep into every detail and crunch the numbers,

ensuring you know exactly what you're doing and why.

Working With US

Is SImple

A couple in a kitchen looks at a phone and laptop. The woman smiles as the man holds the phone.
Get started right away

The best place to start is to connect with us directly. Our commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

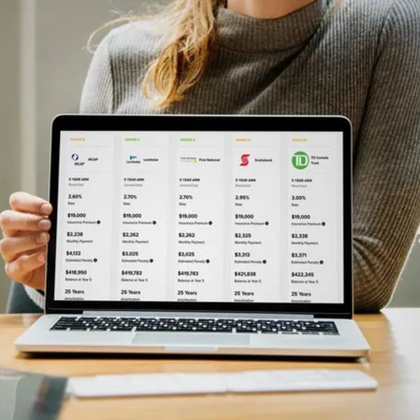
Woman holding a laptop displaying mortgage options from various financial institutions.
Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let us cut through the noise. We'll outline the best mortgage products available with your needs in mind.

Family of three on a couch, watching TV; the man holds a remote control. Woman smiles, child looks serious.
Proceed with confidence

Our goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, we're available to answer any questions you have.

Why Work

With Us?

The Team

Boyce

Collins

BA

Mortgage Broker/ Father/Doomsday Prepper

LEARN MORE

Chris Horrocks BCom

Mortgage Broker/ Father/VW Enthusiast


LEARN MORE
Empty white space.

Steve

McKay

BA

Mortgage Agent L1 Father/ Multi-instrumentalist

LEARN MORE

Trase

Petek

Administrator/Mother of cat and human children/All-around peach

LEARN MORE

Boyce Collins

BA, AMP

License # M08007573

Principal Broker/Father/Doomsday Prepper

LEARN MORE

Steve McKay

BA, AMP

License # M12002405

Mortgage Agent L1 Father/ Multi-instrumentalist

LEARN MORE

Chris Horrocks

BCom, AMP

License # M10002295

Mortgage Broker/Father/VW Enthusiast

LEARN MORE

Trase Petek

Administrator/Mother of cat and human children/

All-around peach

LEARN MORE

Mortgage RESOURCES to keep you informed.

Sharing knowledge and empowering Canadians is in our DNA.

Our blog is filled with tips, tricks and expert advice that can help you save thousands.

By indi Mortgage • October 7, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
By indi Mortgage • September 30, 2026
Financial setbacks happen. Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future. Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward. What lenders look at after a bankruptcy or consumer proposal How long it’s been since your discharge Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then. Your credit rebuild Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly. To be considered fully re-established, lenders typically want to see: Two active trade lines At least two years of clean payment history Credit limits of around $2,500 on each No late or missed payments Your down payment or equity The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options. Your debt service ratios Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify. Conventional vs. insured mortgage options To access the most competitive mortgage products, lenders typically want to see: At least two years plus one day since discharge Fully re-established credit Minimum down payment requirements met Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty) Total debt obligations generally not exceeding 44% of your gross income Alternative lending options Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help. Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward. While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt. Let’s talk about your next step Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available. If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.
By indi Mortgage • September 23, 2026
Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.
Show More
By indi Mortgage • October 7, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
By indi Mortgage • September 30, 2026
Financial setbacks happen. Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future. Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward. What lenders look at after a bankruptcy or consumer proposal How long it’s been since your discharge Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then. Your credit rebuild Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly. To be considered fully re-established, lenders typically want to see: Two active trade lines At least two years of clean payment history Credit limits of around $2,500 on each No late or missed payments Your down payment or equity The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options. Your debt service ratios Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify. Conventional vs. insured mortgage options To access the most competitive mortgage products, lenders typically want to see: At least two years plus one day since discharge Fully re-established credit Minimum down payment requirements met Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty) Total debt obligations generally not exceeding 44% of your gross income Alternative lending options Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help. Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward. While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt. Let’s talk about your next step Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available. If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.
By indi Mortgage • September 23, 2026
Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.

WE PROUDLY SUPPORT

Logo for Kirkendall Neighbourhood Association food drive.
Logo of Good Shepherd with a stylized shepherd's crook and the text
YWCA Hamilton logo with colorful geometric design and text.

Go ahead and schedule a meeting with US!

Get started by completing OUR online mortgage application.

APPLY NOW

We'll let you know exactly where you stand so you can proceed with confidence.