Indi Mortgage Logo

FORMERLY The Personal Mortgage Group

We dive deep into every detail and crunch the numbers,

ensuring you know exactly what you're doing and why.

Logo

FORMERLY The Personal Mortgage Group

We dive deep into every detail and crunch the numbers,

ensuring you know exactly what you're doing and why.

Working With US

Is SImple

A couple in a kitchen looks at a phone and laptop. The woman smiles as the man holds the phone.
Get started right away

The best place to start is to connect with us directly. Our commitment is to listen to your needs, assess your financial situation, provide professional mortgage advice, and guide you through the mortgage process.

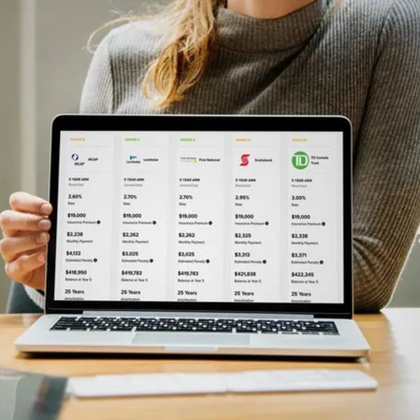
Woman holding a laptop displaying mortgage options from various financial institutions.
Get clarity

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let us cut through the noise. We'll outline the best mortgage products available with your needs in mind.

Family of three on a couch, watching TV; the man holds a remote control. Woman smiles, child looks serious.
Proceed with confidence

Our goal is to make sure you know exactly where you stand at all times. From your initial application through your mortgage renewal, we're available to answer any questions you have.

Why Work

With Us?

The Team

Boyce

Collins

BA

Mortgage Broker/ Father/Doomsday Prepper

LEARN MORE

Chris Horrocks BCom

Mortgage Broker/ Father/VW Enthusiast


LEARN MORE
Empty white space.

Steve

McKay

BA

Mortgage Agent L1 Father/ Multi-instrumentalist

LEARN MORE

Trase

Petek

Administrator/Mother of cat and human children/All-around peach

LEARN MORE

Boyce Collins

BA, AMP

License # M08007573

Principal Broker/Father/Doomsday Prepper

LEARN MORE

Steve McKay

BA, AMP

License # M12002405

Mortgage Agent L1 Father/ Multi-instrumentalist

LEARN MORE

Chris Horrocks

BCom, AMP

License # M10002295

Mortgage Broker/Father/VW Enthusiast

LEARN MORE

Trase Petek

Administrator/Mother of cat and human children/

All-around peach

LEARN MORE

Mortgage RESOURCES to keep you informed.

Sharing knowledge and empowering Canadians is in our DNA.

Our blog is filled with tips, tricks and expert advice that can help you save thousands.

By indi Mortgage • November 4, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
By Steve McKay • October 28, 2026
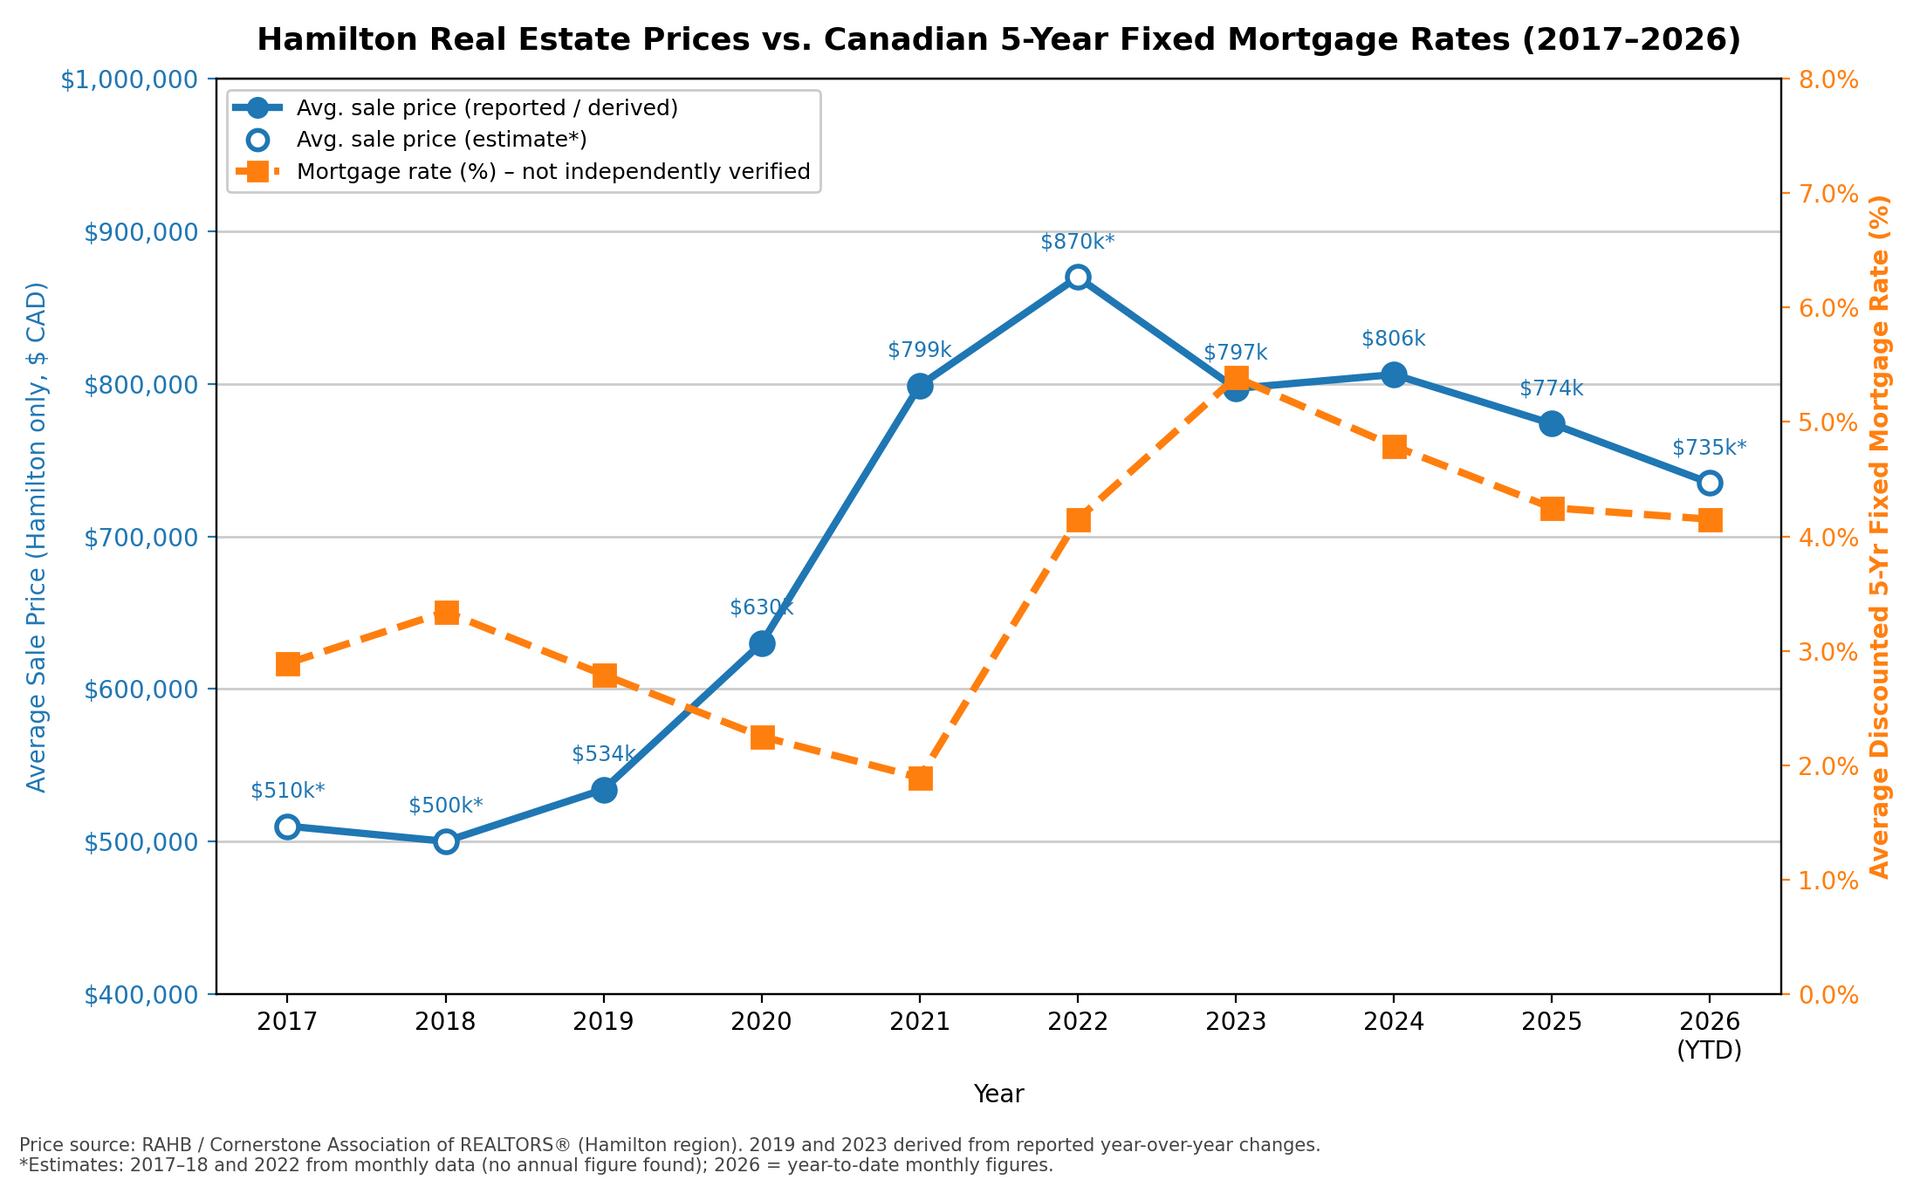
October 2026 Real Estate Update
By Steve McKay • October 28, 2026
Why did the Bank of Canada raise rates and what's next?
Show More
By indi Mortgage • November 4, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
By Steve McKay • October 28, 2026
October 2026 Real Estate Update
By Steve McKay • October 28, 2026
Why did the Bank of Canada raise rates and what's next?

WE PROUDLY SUPPORT

Logo for Kirkendall Neighbourhood Association food drive.
Logo of Good Shepherd with a stylized shepherd's crook and the text
YWCA Hamilton logo with colorful geometric design and text.

Go ahead and schedule a meeting with US!

Get started by completing OUR online mortgage application.

APPLY NOW

We'll let you know exactly where you stand so you can proceed with confidence.